The market
Trophy or Tombstone: What Rent Dispersion Says About the Flight to Quality
Manhattan's finest towers lease for triple the average while half-empty Class B floors rot. The spread is the story of office real estate right now.
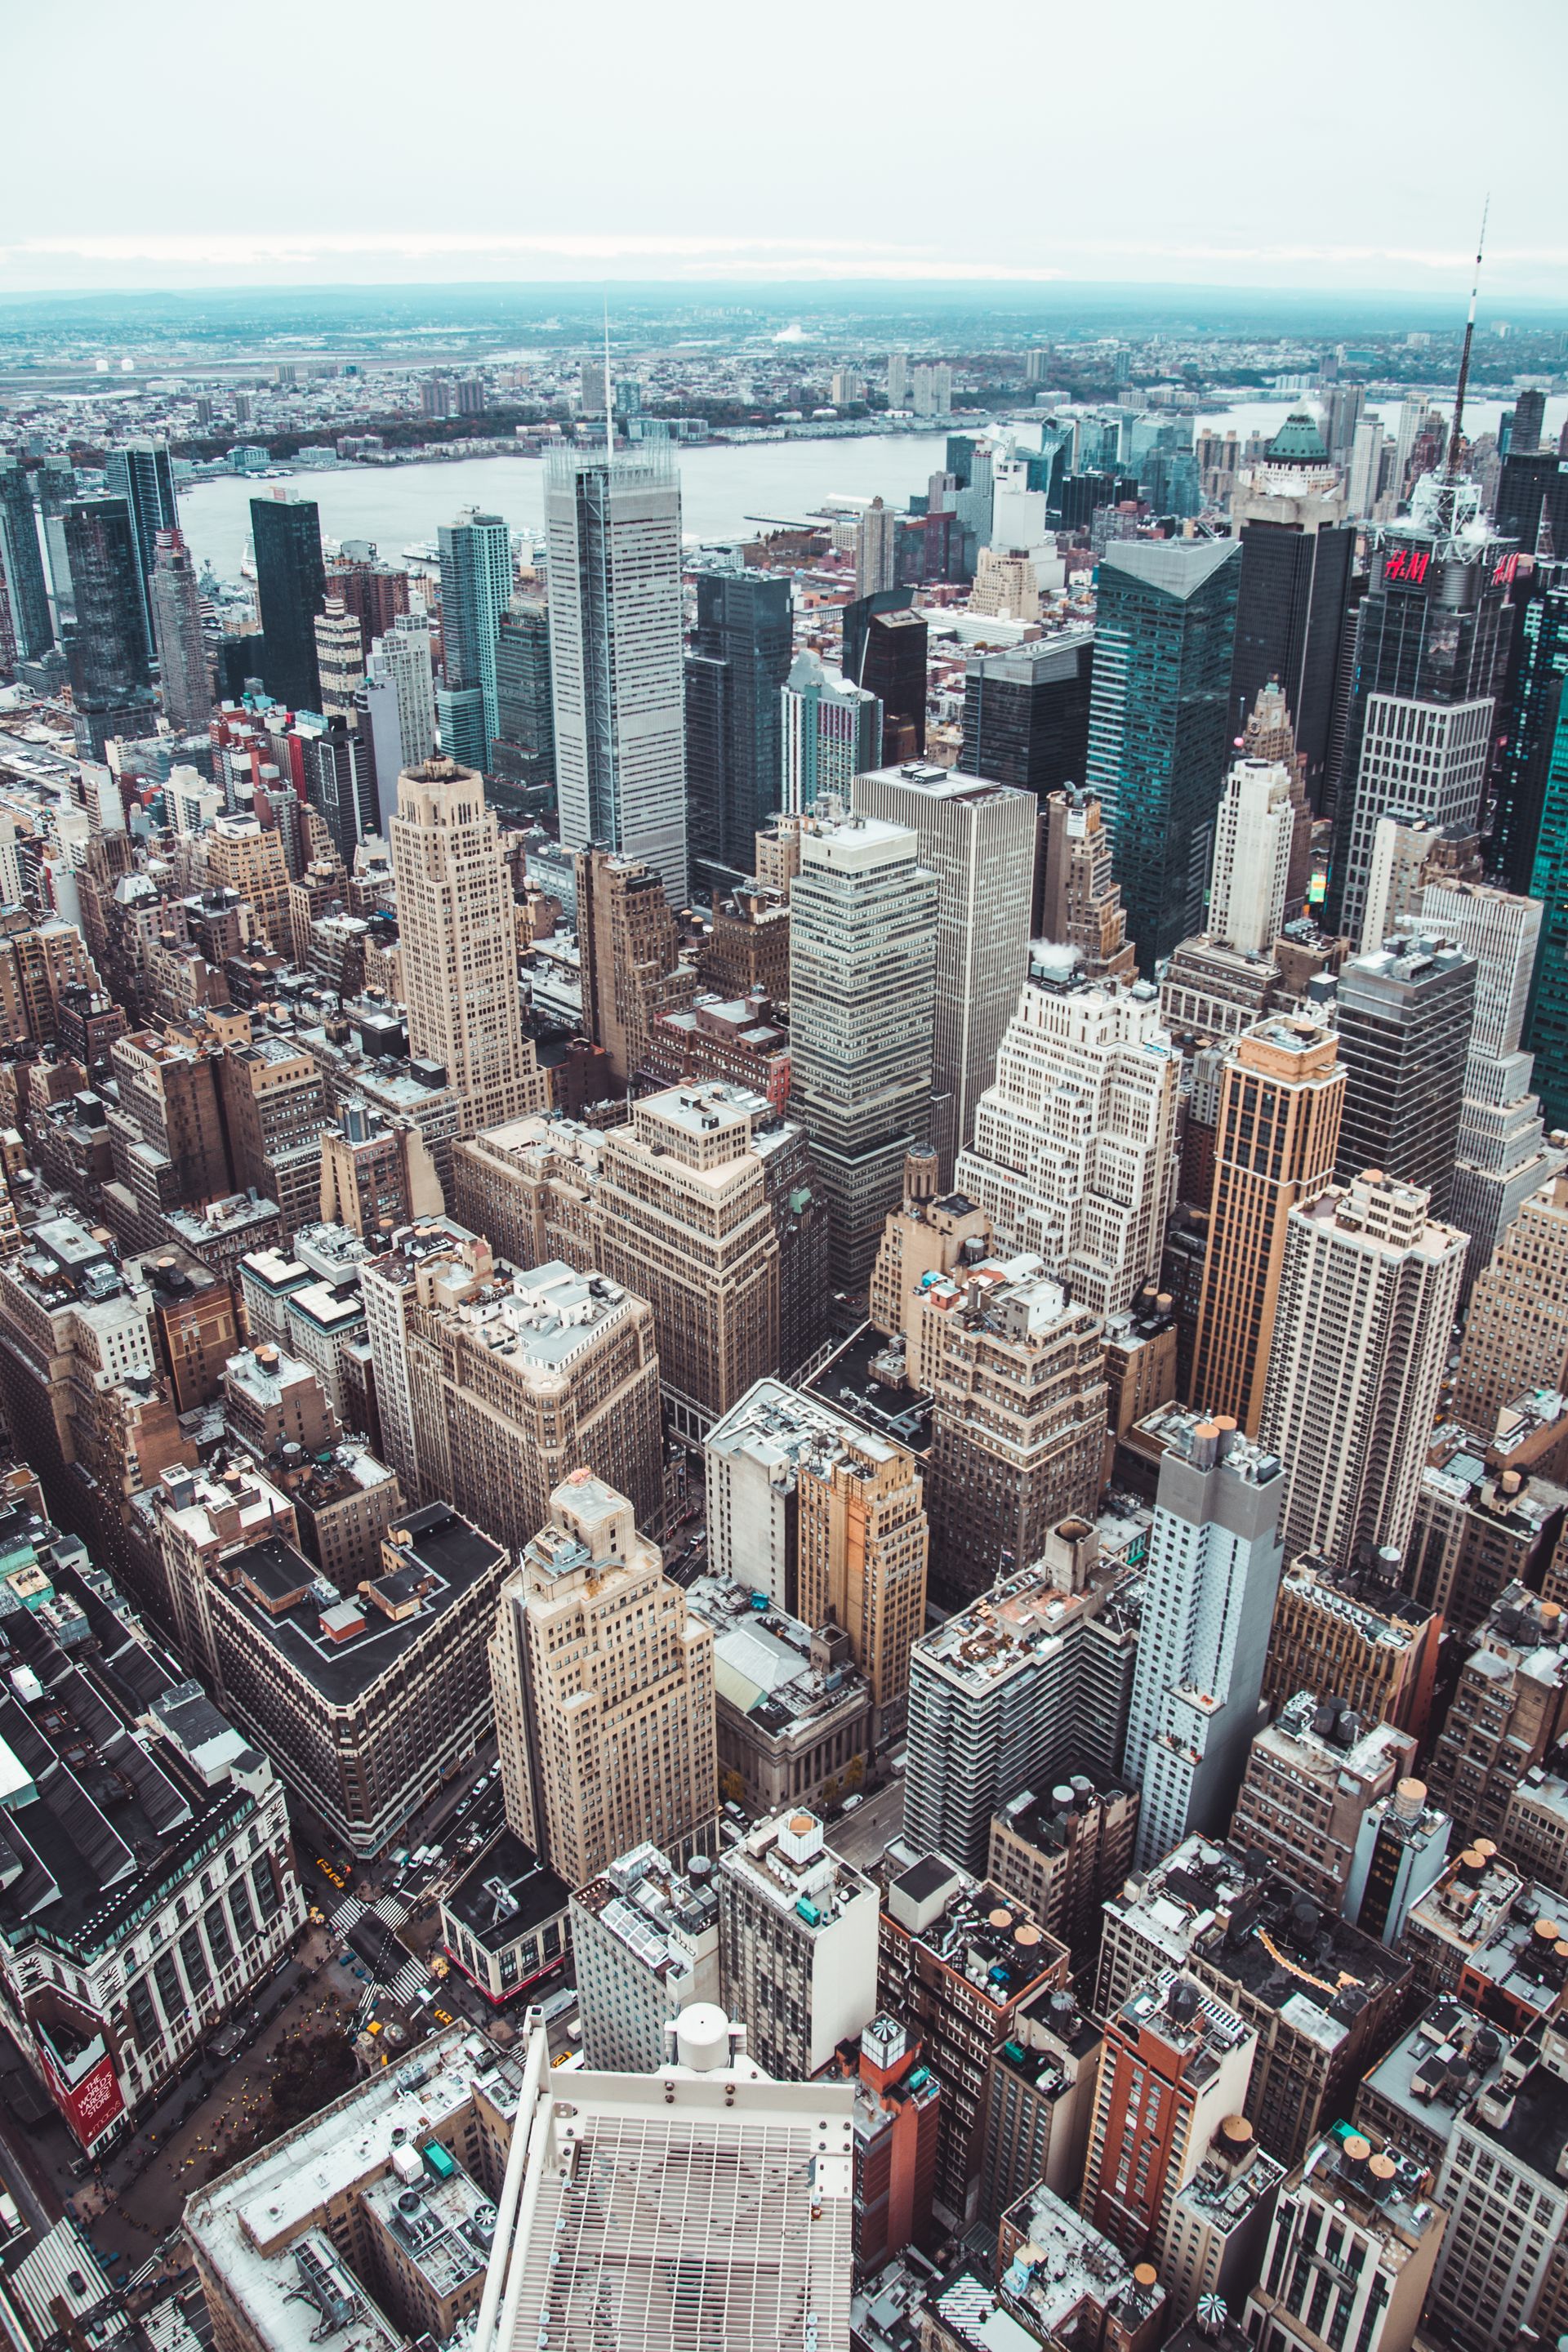
In 2015, Ken Griffin's Citadel agreed to pay roughly $300 per square foot for the top floors of 425 Park Avenue — a number so far above Manhattan's average that the newspapers treated it like a weather event. A decade later, the number that matters isn't the record. It's the gap. One Vanderbilt, the trophy at the corner of 42nd and Vanderbilt, signed rents north of $150 a square foot on its upper floors and leased up ahead of schedule, while in the same borough, whole floors of Class B stock can't find tenants at any price. Manhattan's average asking rent sits just under $80 a foot, per CBRE. The distance between that average and what the top of the market actually clears is the clearest signal in commercial real estate — and it says the office is not dying. It's bifurcating.
The macro backdrop makes the split more dramatic. National U.S. office vacancy crossed 20 percent in 2024, a record, according to Moody's Analytics — the highest in the series' history, above even the 1991 peak. San Francisco, the poster child of the remote-work exodus, watched downtown vacancy climb past 35 percent, with average asking rents falling from the mid-$80s before the pandemic into the mid-$60s. The office CMBS delinquency rate pushed past 11 percent in late 2024, per Trepp, worse than the post-GFC peak. By every headline measure, the asset class is in its worst chapter since the savings-and-loan crisis.
Except it isn't — not all of it. JLL's research has shown that buildings delivered since 2015 have captured the overwhelming bulk of positive net absorption, while older stock sheds tenants by the million-square-foot. The new towers have something the old ones don't: floor-to-ceiling glass, efficient floor plates, real amenities, LEED plaques that corporate sustainability reports require. In an era when the scarce resource is employees willing to commute, the building became the perk. The rent spread between trophy and Class B isn't vanity pricing. It's the market charging tenants for recruitment and retention.
The numbers at the top are extraordinary precisely because they're selective. Griffin's $300 at 425 Park looks less like an anomaly now than an early read of the thesis: if your firm hires 200 people a year, paying triple the rent for a building that helps you close 10 percent more offers is cheap. SL Green's One Vanderbilt — the bet that midtown's best corner deserved a super-trophy — validated it at scale. Meanwhile the mid-range has become the no-man's land. Corporate tenants who once filled 1980s glass boxes either consolidated into trophy space or went remote. The Class B building's tenant pool evaporated, and no discount reliably brings it back. Rent isn't a market here. It's a vote, and the votes are stacking up at the top.
San Francisco supplies the cautionary half of the story. In 2023, 350 California Street sold for roughly $60 million — about a fifth of its pre-pandemic valuation. Downtown Class B buildings have traded at discounts of 60, 70, even 80 percent to their 2019 appraisals. The same landlords who are now offering months of free rent to keep occupancy numbers respectable are quietly writing the equity to zero. Trophy or tombstone is not a metaphor in the Bay Area. It's the actual choice set on the broker's desk.
There is a serious counterargument, and it goes like this: the spread is the opportunity, not the verdict. The conversion wave is rewriting the bottom of the market. In lower Manhattan, 25 Water Street is being converted into 1,320 apartments — the largest office-to-residential conversion in U.S. history. Pearl House at 160 Water is turning an aging tower into 588 apartments. Cities from New York to Denver are rewriting zoning to make these projects pencil. If a significant fraction of obsolete office stock leaves the market entirely, the survivors' vacancy rates recover, and today's $60-a-foot Class B building is tomorrow's income statement for a different asset class. The tombstones may just be future apartments wearing an office costume.
The counter has force, but it also has limits. Conversions work for a narrow band of buildings — the right floor plates, the right zoning, the right neighborhoods. They don't rescue the bulk of the 1970s and 80s inventory scattered across secondary business districts. And conversion math depends on rents and sale prices that make sense today, which means the bottom half of the office market still has to clear at something close to land value before it stabilizes. Dispersion, for now, is the durable condition.
For anyone in the business of rent data, the flight to quality is a strange kind of gift. When every lease in every building clears at the same price, you don't need data — you need a directory. When the spread between the top and the average is 100 percent, and the spread between the top and the bottom is measured in orders of magnitude, every participant needs to know precisely where the line is. Landlords setting asking rents, tenants negotiating tenant-improvement packages, lenders marking loan books: they all need the number on the next lease, on the next floor, in the next building. Dispersion is the raw material of a rent-data franchise. The wider the spread, the more the truth is worth.
The market is telling two stories at once. One says the office is over. The other says the best offices have never been more valuable. Both are true — and the distance between them is where the money is.
This domain is for sale
$18,888
The exact-match .com for the business this article describes. One payment, one secure transfer through Afternic.
Buy CommercialRentData.comQuestions? info@primedomaincapital.com